Homeowner's guide
Roof Insurance Claims: What Is Covered and What Is Not
Storm damage is usually covered, a worn-out roof usually is not, and your insurer is the one who decides. We photograph what is up there and write it up so the storm damage and the older wear are told apart.
Open every day of the week. We answer the phone or call back the same working day.
Yes, usually
What insurance usually covers after storm damage
Homeowners insurance usually covers sudden damage from storms or other events, not the normal wear every roof goes through.
- Shingles or tile that the wind lifted, cracked or tore away
- A limb that came down on the roof during a storm
- An opening the storm left, where rain then got inside
Usually not
What insurance usually leaves out
Damage from age or ordinary wear and tear is often not covered.
- "Underlayment" that has dried out and cracked over the years
- "Granule loss", the bald spots and grit in the gutters on an aging shingle roof
- A "pipe boot" that split as the rubber aged
- "Flashing" that rusted through or worked loose with time
The decision
Who decides coverage
The insurer, not the roofer, decides coverage, approval and payment.
A roofer can show the insurer what is on the roof, and that is where our part ends. Anyone who tells you up front what your claim will pay is guessing at a decision that is not theirs to make.
Your insurer
Reads the claim, decides whether the damage is covered, approves it and pays it.
Us, on the roof
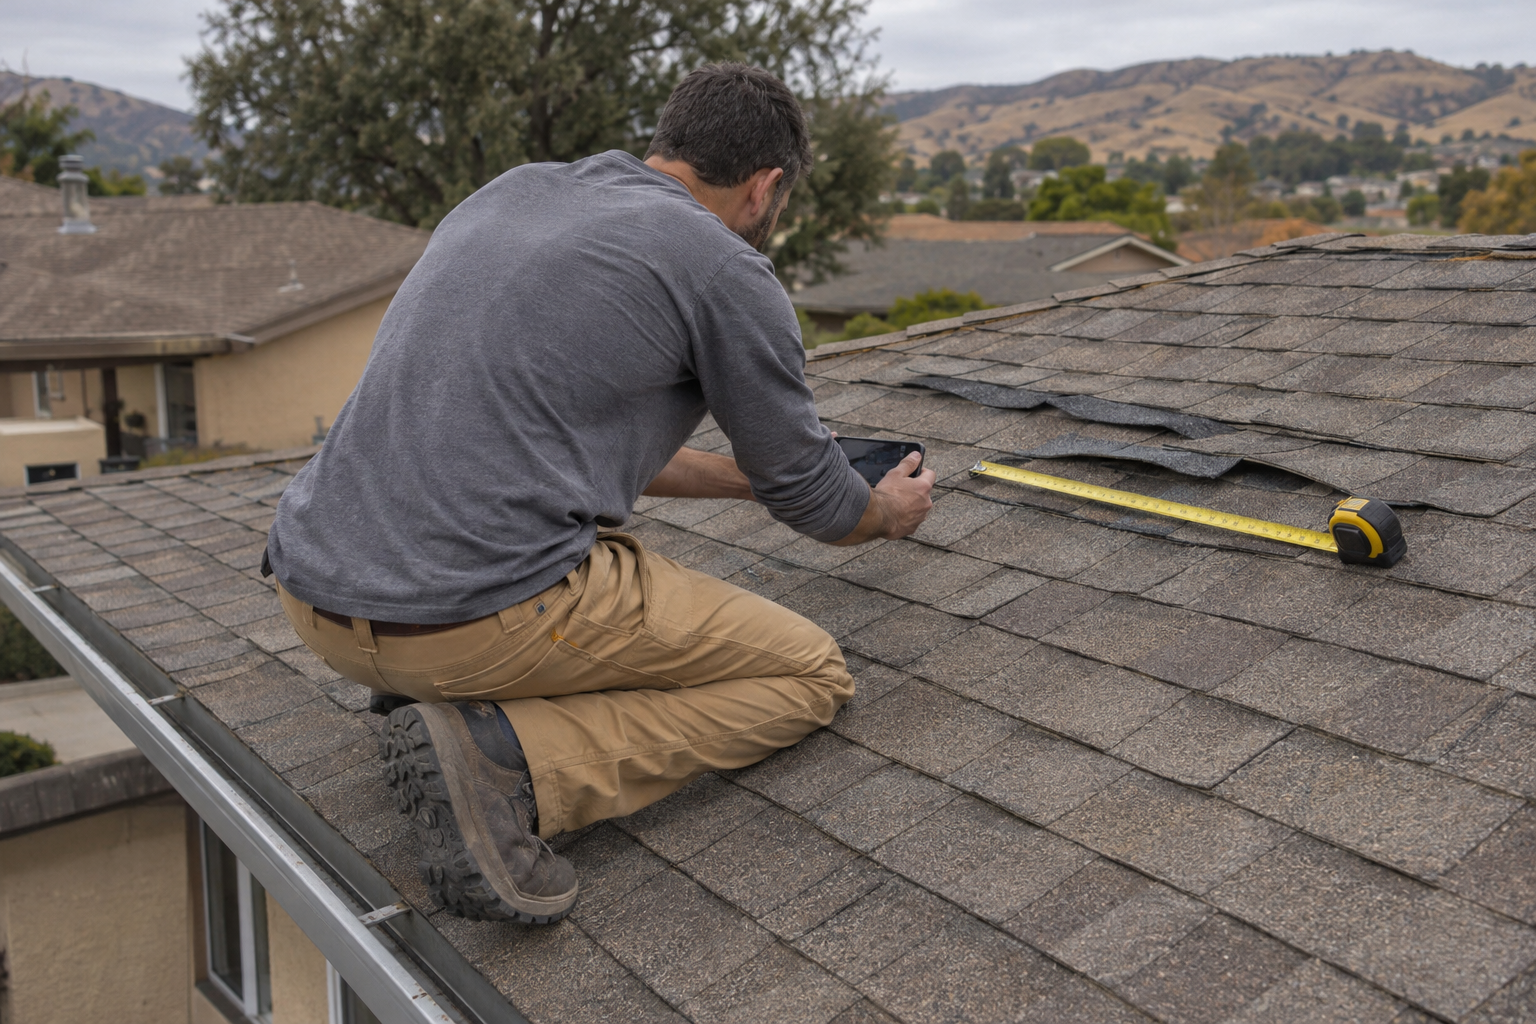
We look the roof over, photograph what we find, set storm damage apart from older wear in writing and quote the repair.
You
You report the damage to your insurer and choose whether to file.
Documentation
Photos and an inspection report
Photos of the damage and a report that separates storm damage from earlier wear help the insurer decide.
Start them before anything on the roof is touched, while the damage is still there to see.
roof inspectionThe records that help a roof claim
Photos
Of the damage before anything is touched and of the repair after, with the hidden layers shot while they are open.
A written report
That sets the storm damage apart from the wear that was already there.
Dates
When the storm came through, when you found the damage and when each repair was made.
Free, no-obligation estimates, with the whole job quoted before we start.
Before you file
More about roof claims
A few more questions come up after storm damage.
Small repairs and claims
You should usually pay for a small wear repair yourself rather than file, since wear is not covered.
A cracked seal, a few loose tabs or a tired "pipe boot" is routine upkeep. A claim makes sense when something sudden did the damage.
State help with a disputed claim
The California Department of Insurance publishes residential claim guides and takes complaints about insurers.
Read its residential property claims guide, listed with the California Department of Insurance residential guides, before you talk to your adjuster.
Google reviews
What neighbors say about us
Reviews from our customers, as they wrote them.
Top notch - Serjio and his team was an absolute pleasure to work with. They were always on time and the most polite and pleasant contractors we have ever had. The whole team went out of the way to make the time at our home as comfortable as possible. I would highly recommend his company.
Thank you. titan roofing I highly recommend them to everybody Five stars all the way
I called Titan Roofing & Rain Gutters inc.for a quote on a residential home, and within minutes they were calling me back and setting up a same day appointment. Sergio came out within the hour and was very professional. He looked everything over and even gave me some great advice in case we ever do experience any leaks. He didn't even have the job but was still willing to help me out.
Storm damage? Let us look before you file.
A call sets the visit. We get on the roof, photograph what we find and tell you plainly what looks like storm damage and what looks like age.
We quote the whole job before we start, with no surprise charges after.